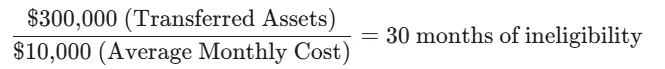Home  ›  Medicaid  ›  Funeral Expense Trust

THE FIRST STEP IN THE MEDICAID SPEND-DOWN PROCESS

Open a protected savings account for your final expenses.

This irrevocable trust, also called a ‘funeral trust,’ acts as a protected savings account for funds to pay for a person’s funeral costs or final wishes.

If your status in Colorado is “Medicaid Pending” and you’ve been told you’ll need to “spend down” your assets for Medicaid approval, this is the first simple step.

The dollar-for-dollar trust works as a secure savings account for final expenses, ensuring you don’t overfund. You can choose a term of 1, 3, or 5 years that best fits your needs.

Family making dinner together

Needing to qualify for a Medicaid Spend-down?

The first step in qualifying should be the Funeral Trust Program.

  • Immediate exemption from Medicaid, not subject to the “five-year look back” (up to $15,000 in Colorado).
  • Applicants are not required to go to a specific funeral home.
  • No attorneys’ fees; the trust is already established.
A family with peace of mind
Family at a celebration of life

Why Choose the Funeral Trust Program?

  • Policy benefits are paid directly to the funeral home or cemetery.
  • Creditors cannot attach funds used for funeral expenses.
  • Policy benefits are tax-exempt.
  • No attorney fees; the trust is already established.
  • Immediate exemption from Medicaid.
  • Applicants are not required to go to a funeral home.
  • Families can permanently set aside money for funeral expenses.
  • The policy is portable to any funeral home in all 50 states.
Scott Behan

“The funeral trust program is the easiest and quickest program that is used for immediate Medicaid asset protection that I have seen and used.”

Scott Behan

Certified Preplanning Consultant — Author: Funeral Funding Made Simple & Speaking from The Heart: Advanced Funeral Planning

What Does This Type of Trust Do?

This is an insurance product that protects your final-expense funds from Medicaid spend-down and the 5-year lookback. We are not Certified Medicaid Planners or attorneys — always seek advice from a qualified attorney regarding all legal concerns.

Anyone, ages 0 to 99

The funeral trust has no underwriting, so everyone qualifies.

Protected by an insurance company

The funeral home does not handle the money. The insurance company safeguards it.

Paid out income tax-free

Always paid out income tax-free to the funeral home and/or estate.

Dollar-for-dollar plan

You choose how much you can pay and select a 1-, 3-, or 5-year plan, then cover what you can.

Doing nothing can cost

Medicaid reduces elderly people’s allowable assets to just $2,000 if not protected.

The funds are guaranteed

Funds are immediately available and paid within 48 hours of the claim.

Dan Wilson

“Once you find yourself incapacitated and medicated, it’s like missing the boat to get your ducks in a row — trust me, it’s a lot harder to organize your life in the middle of the chaos.”

Dan Wilson

Licensed Life and Health Insurance Agent | MedPending Colorado Rep

Are There Payment Options?

An ideal plan for someone on a fixed income is to set aside what you can afford while staying within budget — starting at $25/mo.

Single Pay

Single Pay

A single lump-sum payment to an irrevocable trust protects it.

1-Year Plan

1-Year Plan

Monthly payments over 12 months.

3-Year Plan

3-Year Plan

Monthly payments over 36 months.

5-Year Plan

5-Year Plan

Monthly payments over 60 months.

Stories

The Proactive Plan: The Chen Family (Had an Irrevocable Trust)

The Setup

Four years before Mrs. Chen needed care, she and her husband, Mr. Chen, met with an elder-law attorney. They decided to create an Irrevocable Trust and transferred some non-exempt assets (a little savings and a modest brokerage account) into it.

The Event

In 2025, four years after establishing the trust, Mrs. Chen suffered a significant stroke and required skilled nursing home care at $12,000 per month. Their assets were insufficient to cover this indefinitely.

The Outcome — No Spend-Down on Trust Assets

When they applied for Medicaid, the assets in the Irrevocable Trust were not counted, because they had protected the funeral costs. Their spend-down consumed her existing assets and her monthly income, which was contributed toward her care. The Chen family celebrated her life the way she would have wanted, preserving their legacy.

The Late-Stage Panic: The Miller Family (Money Given Away Within the Look-Back Period)

The Setup

Mr. Miller, a widower, was diagnosed with early dementia in 2022. Concerned about his declining health, his daughter met with a friend who advised transferring assets totaling $300,000 out of his accounts in January 2023.

The Event

In January 2025, just two years after moving the funds, Mr. Miller’s condition worsened and he needed immediate long-term care.

The Outcome — Medicaid Penalty Imposed

Because the $300,000 was transferred within the five-year look-back period, Medicaid deemed it an improper transfer and calculated a penalty period by dividing the amount by the state’s average monthly cost of care (about $10,000). The family had to pay for roughly 30 months of care before Medicaid would begin covering expenses — and ended up taking out a reverse mortgage on the home they had intended to protect.

Miller Family penalty calculation

The Unprepared: The Garcia Family (No Trust)

The Setup

Mr. and Mrs. Garcia relied on Medicare and modest savings and never engaged in long-term-care planning, with only simple Wills. Their only significant asset was their home, valued at $400,000, plus $150,000 in a joint savings account.

The Event

In 2024, Mrs. Garcia fell and required permanent residency in a long-term-care facility.

The Outcome — Forced Spend-Down

To qualify, Mrs. Garcia could only keep a minimal amount of countable assets. Mr. Garcia (the community spouse) could keep the home and a protected share of the savings (the Community Spouse Resource Allowance), but their combined savings were over the allowance, so they had to spend down the excess on her care. After his passing, the state’s Medicaid Estate Recovery Program could place a lien on the home to recoup costs.

The Hidden Risk: The Wilson Family (A Revocable Living Trust)

The Setup

The Wilsons were told a Revocable Living Trust was essential for avoiding probate, so they created one five years ago, placing their home and investments inside — but retained the power to take the assets out whenever they wanted.

The Event

In 2025, Mr. Wilson developed Alzheimer’s and needed long-term care.

The Outcome — The Trust Was Countable

Because a Revocable Trust lets the owner take assets back at any time, Medicaid considers those assets available to the applicant. The home and investments were not protected, and the family faced the same spend-down as the Garcia family. They avoided probate, but did not achieve Medicaid asset protection.
Keep Up, Get in Touch

Reach out and someone will help you set up a protected savings account for your final expenses.

MedPending is a resource provided by Paycheck Benefits LLC.